
If you have started earning money from a rental property, dividend stocks, or a small business you are not actively running, you have probably wondered how that income gets taxed. The answer varies considerably depending on the source, which is why the different types of passive income each carry their own specific tax treatment. The honest answer is more complicated than most people expect, mostly because the IRS uses a different definition of passive income than the one used in everyday conversation.
This article walks through exactly how passive income tax works, what the IRS actually counts as passive, how different types of passive income get taxed, what deductions are available, and the common mistakes that cause people to overpay or run into trouble at filing time. This is useful knowledge whether you are a landlord, a dividend investor, someone earning from online passive income streams, or someone building income streams that fit around the rest of your life.
Table of Contents
The IRS Definition of Passive Income Is Not What You Think
When most people hear “passive income,” they think of anything that earns money without active daily work: rental properties, dividend stocks, interest, royalties, and online business income. The IRS has a much narrower definition, and understanding the gap between the two is the most important thing in this entire topic.
The IRS draws a clear line between income earned through active work and income that arrives without daily active participation. For tax purposes, the IRS defines passive income as money earned from one of two specific categories:
Income from a trade or business in which the taxpayer does not materially participate Income from rental activities, regardless of how much you participate, unless you qualify as a real estate professional
Here is the part that surprises most people. Dividends, interest, and capital gains from investments are not classified as passive income under IRS rules. They fall into a separate category called portfolio income. This distinction matters because passive income and portfolio income follow different tax rules, particularly around how losses can be used.
So when someone says they earn passive income from dividend stocks, that is accurate in everyday language but technically inaccurate for tax purposes. The passive income tax rules specifically apply to rental properties and business activities where you are not materially involved, not to your stock portfolio.
Material Participation: The Test That Determines Everything
Whether your income counts as passive for tax purposes comes down to something called material participation. If you materially participate in a business, the income is non-passive and gets reported and treated differently than if you do not.
The IRS uses seven tests to determine material participation. Meeting any one of these tests means you materially participated in the activity, which makes the resulting income non-passive:
You worked more than 500 hours in the activity during the year Your participation was substantially all the participation in the activity by anyone You worked more than 100 hours and at least as much as any other individual involved The activity is a significant participation activity, and your combined participation in all such activities exceeds 500 hours You materially participated in the activity for any 5 of the prior 10 years The activity is a personal service activity, and you materially participated in any 3 prior years Based on facts and circumstances, you participated on a regular, continuous, and substantial basis
If none of these apply to you, the income is passive, and a specific set of passive income tax rules applies, particularly around how you can use any losses from that activity.
How Different Types of Passive Income Are Actually Taxed
Rental Property Income
Rental real estate is the clearest example of passive income tax in practice, and understanding the tax rules before you acquire property is one of the most valuable parts of building real estate income on a sound financial foundation. The IRS treats rental income as passive almost automatically, even if you actively manage the property yourself, with one major exception covered later.
Rental income is taxed as ordinary income at your regular tax bracket rate. The good news is that you are taxed on net rental income, not gross rent collected. Deductible expenses against rental income include:
Mortgage interest Property taxes Insurance premiums Property management fees Repairs and maintenance Depreciation, which lets you deduct a portion of the property’s value each year over 27.5 years for residential property
After these deductions, what remains is your taxable rental income. For many landlords, especially in the early years of ownership when depreciation and interest deductions are largest, rental properties can show a loss for tax purposes even while generating positive cash flow.
The Real Estate Professional Exception
If you qualify as a real estate professional under IRS rules, your rental income and losses are treated as non-passive rather than passive. To qualify, you must meet both of these requirements:
More than half of your total working hours across all trades or businesses during the year were in real estate activities where you materially participated You performed more than 750 hours of services in real estate activities during the year
This status matters enormously for tax purposes because it removes the passive activity loss limitations described below, allowing real estate losses to offset other income without restriction.
The $25,000 Special Allowance
Even without real estate professional status, there is a special allowance built into the passive income tax rules. If you actively participated in a rental real estate activity, meaning you made management decisions like approving tenants and setting rental terms, you can deduct up to $25,000 of passive losses from that activity against your non-passive income, such as your salary.
This allowance phases out as your modified adjusted gross income rises above $100,000 and disappears completely above $150,000. For someone with an MAGI of $120,000, the allowed deduction drops to $15,000 instead of the full $25,000.
Dividend Income
As covered above, dividends are technically portfolio income for tax purposes, not passive income, but they are commonly discussed alongside passive income tax topics because most people earn them passively in the everyday sense.
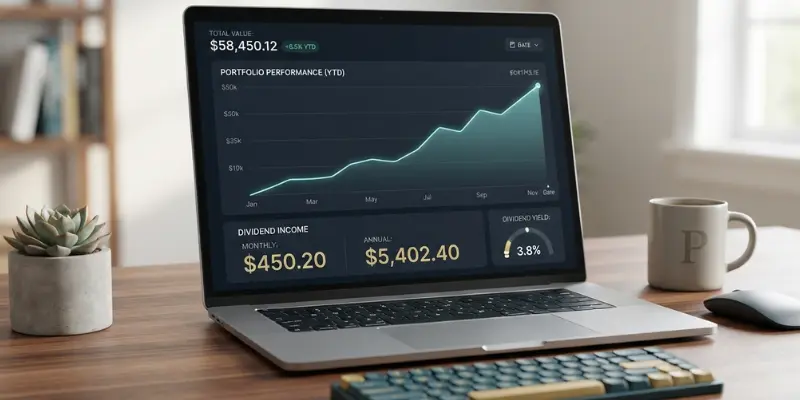
Qualified dividends are taxed at the lower long-term capital gains rates, which for most taxpayers fall at 0, 15, or 20 percent depending on total taxable income. Non-qualified or ordinary dividends are taxed at your regular income tax rate, the same as wages.
The distinction between qualified and non-qualified dividends depends on how long you held the stock and what type of company paid the dividend. Most dividends from US companies held for the required holding period qualify for the lower rate.
Interest Income
Bank account interest, certificate of deposit interest, and bond interest are taxed as ordinary income at your regular tax bracket, with no preferential rate. This applies whether the interest comes from a high-yield savings account or a corporate bond.
Municipal bond interest is a notable exception. Interest from municipal bonds is generally exempt from federal income tax and, in many cases, from state tax as well if you live in the state that issued the bond. This makes municipal bonds attractive specifically for their tax treatment, even when their stated yield is lower than a comparable taxable bond.
Royalty Income
Royalties from books, music, patents, and other intellectual property are generally treated as passive income if you are not materially involved in producing new versions of the work. If you wrote one book years ago and still collect royalty checks, that income is passive. If you are actively writing new editions or actively promoting and managing the intellectual property as an ongoing operation, the income may be reclassified as active and subject to self-employment tax.
This distinction trips up a lot of authors and creators who assume royalty income is automatically passive. The IRS looks at your actual level of ongoing involvement, not just the source of the income.
Passive Activity Loss Rules
This is where passive income tax rules get genuinely important for anyone with rental properties or business interests they do not actively manage.
The general rule is that passive losses can only be deducted against passive income. If you have a loss from a rental property, you generally cannot use that loss to reduce the tax on your salary or your business income, unless you qualify for the real estate professional exception or the $25,000 special allowance described above.
If your passive losses exceed your passive income in a given year, the excess loss does not disappear. It carries forward to future years, where it can offset future passive income. The loss can also be used in full in the year you sell or dispose of the entire passive activity in a fully taxable transaction.
This rule exists specifically to prevent people from using passive real estate losses, which are common due to depreciation, to artificially reduce taxes on their regular salary income without significant restriction.
The Net Investment Income Tax
Higher earners need to be aware of an additional tax that applies to certain passive and portfolio income. The Net Investment Income Tax, often called NIIT, is a 3.8 percent surtax on net investment income for individuals above specific income thresholds.
The threshold for individual filers is $200,000 of modified adjusted gross income. For married couples filing jointly, the threshold is $250,000. If your income exceeds these levels, you may owe an additional 3.8 percent on the lesser of your net investment income or the amount your MAGI exceeds the threshold.
Income subject to NIIT includes interest, dividends, capital gains, rental income, and royalties. This tax stacks on top of your regular income tax on these sources, which means high earners with significant passive income tax exposure should plan for this additional layer when estimating their total tax liability.
RELATED POSTS
Online Passive Income: What Actually Works and What Just Sounds Good
How to Make a Passive Income: 25 Proven Ways to Earn Money While You Sleep (2026–2030)
Self-Employment Tax and Passive Income
One of the genuine advantages of properly classified passive income is that it generally avoids self-employment tax, which is 15.3 percent and applies to active self-employment earnings to cover Social Security and Medicare.
Rental income that qualifies as passive is not subject to self-employment tax, even though it is taxed as ordinary income. This is a meaningful distinction. A landlord earning $30,000 in net rental income pays regular income tax on that amount but does not pay the additional 15.3 percent that would apply if the same income came from active self-employment.
This is part of why correctly understanding your activity’s passive or non-passive classification matters so much for total tax liability, not just for loss limitation purposes.
Tax-Advantaged Accounts and Passive Income
One of the most effective ways to reduce passive income tax exposure is to hold investments inside tax-advantaged accounts.
A Roth IRA allows dividends, interest, and capital gains to grow completely tax-free, with no tax owed on withdrawals after age 59 and a half, provided the account has been open at least five years. This eliminates the passive income tax question entirely for investments held inside the account.
A traditional IRA or 401k defers taxes until withdrawal, which can be useful if you expect to be in a lower tax bracket in retirement than you are now.
Health Savings Accounts offer similar tax-free growth specifically for medical expenses, and 529 plans offer the same for education expenses.
For anyone building a meaningful dividend stock portfolio for passive income, holding those positions inside a Roth IRA, rather than a regular taxable brokerage account, can meaningfully reduce the long-term tax burden on that income stream, particularly for high-yield holdings that would otherwise generate a significant annual tax bill.
Common Passive Income Tax Mistakes
Assuming all passive-sounding income is taxed the same way. Rental income, dividends, interest, and royalties each follow different rules. Treating them as interchangeable for tax purposes leads to errors.
Forgetting depreciation recapture. When you sell a rental property, the depreciation you claimed over the years gets “recaptured” and taxed, typically at a maximum rate of 25 percent. Many property owners are surprised by this bill at sale time because they forgot the depreciation deductions they took every year along the way.
Not tracking material participation hours. If you are trying to qualify as a real estate professional or trying to establish active participation for the special allowance, keeping a log of hours spent is essential. Without documentation, these claims are difficult to defend if questioned.
Missing the NIIT threshold. High earners sometimes fail to account for the additional 3.8 percent surtax when estimating their tax liability on passive and portfolio income, leading to an underpayment penalty.
Not using Schedule E correctly. Rental and passive business income generally needs to be reported on Schedule E, which has specific sections for passive and non-passive income. Misreporting here can trigger errors in how losses are applied.
How to Plan Ahead for Passive Income Tax
Understanding passive income tax rules before you build a significant income stream is far more useful than trying to fix problems after the fact. The same applies to the income-building process itself: people who understand how passive income actually gets built tend to structure their investments and activities in ways that make the tax picture much cleaner from the start.
If you are building a rental property portfolio, consider whether pursuing real estate professional status makes sense for your situation, particularly if you have substantial losses you want to use against other income.
Students building their first investment or passive income accounts have a particular advantage here: opening a Roth IRA early means decades of tax-free compounding, and students who start building income and investing early often end up with dramatically lower lifetime tax burdens on their passive income than people who start later. If you are building a dividend portfolio, prioritize holding high-yield or non-qualified dividend positions inside a Roth IRA or traditional IRA where possible, since those structures eliminate or defer the tax bill entirely.
If you earn interest or dividends through a passive income app or investment platform, those earnings are still fully taxable even though the app handles the mechanics automatically. If you are earning royalty income from creative work, keep clear records of your level of ongoing involvement, since this determines whether the income is treated as passive or subject to self-employment tax.
If your income is approaching the NIIT thresholds, work with a tax professional to understand whether the additional 3.8 percent surtax applies and how to plan around it.
Building income that works without trading constant hours for it is valuable specifically because it changes your relationship with time. And just like taking the first step toward earning outside your regular job requires some upfront planning, understanding the passive income tax rules before you start building a meaningful income stream saves considerable pain later. Understanding the tax rules that govern that income protects more of what you build and prevents unpleasant surprises when you file.
Conclusion: Passive Income Tax Rewards Preparation
Passive income tax is not as simple as “passive income gets taxed less.” The reality is a layered system with different rules for rental income, dividends, interest, and royalties, each carrying its own rate structure, deduction opportunities, and limitations.
The people who benefit most from passive income, after tax, are the ones who understood these rules before building their income streams rather than after. A rental property held with an eye toward the real estate professional exception, a dividend portfolio held inside a Roth IRA, and accurate tracking of material participation hours all make a measurable difference in what you actually keep.
None of this requires becoming a tax expert. It requires understanding the basic categories, knowing which apply to your specific income streams, and working with a tax professional when the stakes are significant enough to justify it. The tax code rewards people who plan ahead, and passive income tax is no exception.
Frequently Asked Questions About Passive Income Tax
Is passive income taxed differently than active income?
In most cases, passive income is taxed at the same federal income tax rates as active income. However, passive losses are generally limited to offsetting passive income, and properly classified passive income is usually not subject to self-employment tax.
Are dividends considered passive income for tax purposes?
Not technically. The IRS classifies dividends as portfolio income rather than passive income. Qualified dividends may receive lower long-term capital gains tax rates, while non-qualified dividends are taxed as ordinary income.
What is the passive activity loss limitation?
This IRS rule generally allows passive losses to offset only passive income. Rental property losses usually cannot reduce salary or other active income unless you qualify for specific exceptions.
What is the $25,000 special allowance for rental losses?
If you actively participate in managing a rental property, you may deduct up to $25,000 of rental losses against non-passive income. The allowance gradually phases out between $100,000 and $150,000 of modified adjusted gross income.
What is the Net Investment Income Tax?
The Net Investment Income Tax (NIIT) is a 3.8% surtax that applies to certain investment income for individuals whose modified adjusted gross income exceeds IRS thresholds.
Does rental income count toward self-employment tax?
No. Rental income that qualifies as passive income is generally not subject to the 15.3% self-employment tax, although it remains subject to regular income tax.
How can I reduce taxes on my passive income?
Using tax-advantaged accounts such as Roth IRAs or Traditional IRAs, maintaining accurate records, and understanding rental property tax rules can help reduce taxes. For larger portfolios, working with a qualified tax professional is often beneficial.
What happens if I qualify as a real estate professional?
If you qualify as a real estate professional under IRS rules, rental income and losses may be treated as non-passive. This can allow rental losses to offset wages and other active income, provided all eligibility requirements are met.

3 Comments
Pingback: What Is Passive Loss? Rules, Limits & Examples
Pingback: Side Hustles You Can Do From Your Phone (14 Real Ideas)
Pingback: AI Side Hustles 2026: 12 Realistic Ways To Earn